Indonesia
 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
Let’s Get Deep Inside IPD Management System Online
Other |
2026-09-16 07:05:45
Buying equipment can be a major expense for any business. Whether you need machines, tools, vehicles, or other essential items, the cost can affect your business budget. Many businesses use financing to purchase equipment without paying the full amount upfront. However, choosing the wrong loan can lead to higher interest costs and difficult monthly payments.
An equipment loan calculator can help you understand your possible financing costs before you apply for a loan. It allows you to estimate monthly payments, review different loan terms, and see how the amount you borrow may affect your budget. With this information, you can make a more informed decision and avoid taking on unnecessary costs.
Smart Business Credit understands the importance of careful financial planning when a business needs new equipment. Learning how to estimate loan payments can help you prepare for future expenses and choose financing that fits your business needs.
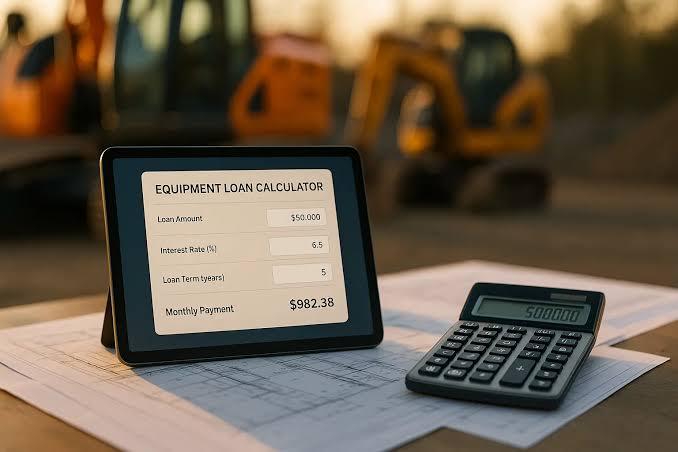
An equipment loan calculator is a simple financial tool that estimates the cost of borrowing money to purchase business equipment. It usually asks for details such as the loan amount, interest rate, and repayment term.
After you enter these details, the calculator estimates your monthly payment. Depending on the tool, it may also show the total interest you could pay and the overall cost of the loan.
For example, imagine your business needs equipment worth $30,000. You plan to finance the purchase instead of paying the full amount from your available cash. By entering the expected loan amount, interest rate, and repayment period, you can estimate what the monthly payments might look like.
These estimates help you understand whether the financing option is suitable for your budget before you make a commitment.
Reducing financing costs does not always mean finding the lowest monthly payment. It also means understanding the total amount you may pay over the life of a loan.
An equipment loan calculator helps you compare different financing choices and see how small changes can affect the total cost.
The repayment term is the amount of time you have to repay a loan. Some equipment loans have shorter repayment periods, while others allow payments over several years.
A longer loan term can reduce your monthly payment because the amount borrowed is spread over more months. However, you may pay more interest over time.
A shorter loan term usually means higher monthly payments, but it may reduce the total interest paid.
Using an equipment loan calculator allows you to compare these options before choosing a repayment period. You can select a term that balances affordable monthly payments with a reasonable overall cost.
The interest rate is one of the most important factors affecting your financing costs. Even a small difference in the rate can change the total amount you pay.
For example, two lenders might offer financing for the same equipment at different interest rates. The monthly payments may appear similar at first, but the total cost could be different.
An equipment loan calculator helps you estimate these differences. You can enter different interest rates and compare the results to understand how the rate affects your budget.
Before accepting a financing offer, review the actual interest rate and ask whether it is fixed or variable. A fixed rate generally stays the same during the agreed period, while a variable rate may change according to the loan terms.
A down payment is the amount you pay upfront when purchasing equipment. The remaining balance may be covered by a loan.
A larger down payment can reduce the amount you need to borrow. When you borrow less money, your monthly payments and total interest costs may also decrease.
For example, if equipment costs $25,000 and you pay $5,000 upfront, you would need to finance the remaining $20,000, before any additional fees or other costs.
You can use an equipment loan calculator to compare different down payment amounts and estimate how they affect your payments.
However, avoid using all your available business cash for an upfront payment. Your business may still need money for payroll, supplies, rent, maintenance, and unexpected expenses. The right down payment should reduce borrowing costs without leaving your business short of working capital.
A business needs a clear budget to manage its daily operations. Equipment financing adds another regular expense, so it is important to understand how loan payments will fit into your financial plan.
Knowing your estimated monthly payment helps you decide whether your business can afford the equipment.
You can compare the expected payment with your regular income and operating expenses. This gives you a clearer idea of how much money will remain available after paying the loan.
An equipment loan calculator can help you prepare for this expense before you submit a financing application.
Keep in mind that the estimated payment may not include every cost. Insurance, maintenance, taxes, documentation fees, and other charges may increase the total expense of owning the equipment.
Working capital is the money a business uses to cover everyday expenses. It may include employee wages, inventory, rent, utilities, and supplier payments.
If you choose equipment financing without planning carefully, monthly payments could place pressure on your working capital.
A calculator helps you estimate the loan payment and consider whether it leaves enough money for other business needs. This is especially useful for small businesses that must manage limited cash resources.
The goal is not simply to purchase equipment. It is to purchase equipment while keeping the business financially stable.
Business income may change throughout the year. Some companies have busy seasons followed by slower periods. Others experience changes in customer demand or unexpected operating expenses.
Before accepting a loan, consider whether you could continue making payments during a slower month.
An equipment loan calculator helps you understand the expected payment, but you should also review your income records and prepare a realistic budget. If the payment would become difficult during a slow period, consider a lower loan amount or a different repayment structure.
Yes. Comparing financing offers is one of the most useful ways to identify a loan that may cost less.
Different lenders can offer different interest rates, repayment terms, fees, and conditions. Looking only at the monthly payment may not show which option is more affordable overall.
When reviewing loan options, compare more than the monthly payment. Look at the total interest, fees, repayment period, and overall amount you may need to repay.
For example, one offer might have a lower monthly payment because it has a longer repayment term. Another might require higher monthly payments but result in less interest over the full term.
An equipment loan calculator allows you to test different loan amounts, rates, and terms. You can then use the results to ask lenders better questions and understand the differences between their offers.
Always confirm whether the lender charges origination fees, early repayment penalties, or other additional costs. These expenses may not be included in a basic calculator's estimate.
A calculator provides estimates based on the information you enter. It does not replace the official loan agreement.
Before signing, review the repayment schedule, interest terms, fees, late payment charges, and any conditions related to the equipment.
If a lender offers a payment that seems unusually low, ask how the payment is calculated and whether a large final payment is required. Understanding these details can help you avoid unexpected expenses.
To get useful results, enter accurate information and compare realistic financing options. A calculator is most helpful when the figures reflect the equipment purchase you are actually considering.
Start by identifying the price of the equipment. If you expect to pay extra for delivery, installation, or setup, include those expenses in your overall budget.
Then subtract the down payment you plan to make to estimate how much you need to borrow.
Enter the interest rate offered by a lender or use a reasonable estimate for early planning.
If you have several financing offers, calculate each one separately. This makes it easier to compare the potential costs.
Remember that an estimated rate may differ from the final rate you qualify for.
Choose the repayment term you want to evaluate. You can compare several periods to see how the monthly payment and total interest may change.
Do not choose a longer term only because it lowers the monthly payment. Consider the total cost and how long you plan to use the equipment.
Check the estimated monthly payment and any available information about total interest and repayment costs.
Then compare the results with your business budget. Consider whether you can make the payments comfortably while covering other operating expenses.
Repeat the calculation with different loan amounts, down payments, interest rates, and repayment terms.
This helps you understand which changes could lower your financing costs. Once you identify a suitable option, confirm the actual terms and fees with the lender.
The purchase price and loan payment are only part of the total cost of owning business equipment. Planning for additional expenses can help you avoid financial pressure later.
Equipment may need regular servicing, replacement parts, or repairs. These costs can vary depending on the type, age, and condition of the equipment.
Include a reasonable maintenance allowance in your budget so that repair bills do not interfere with your loan payments.
Some equipment may require insurance, registration, or taxes. The exact requirements depend on the equipment and your location.
Check these expenses before making a purchase. Adding them to your financial plan gives you a more complete picture of the cost.
Large machines and specialized equipment may require transportation, installation, or employee training. These services can increase the amount you need to spend.
If these costs are financed as part of the loan, they may also affect your repayment amount and interest expenses.
Equipment can sometimes stop working because of maintenance needs or unexpected problems. This may delay production or reduce business income.
Choose equipment that fits your business requirements and consider its expected reliability. A low purchase price may not always mean a lower long-term cost if repairs are frequent.
A calculator can support better financial decisions, but the results depend on the information you provide. Avoiding a few common mistakes can make your estimates more useful.
A low monthly payment can look attractive, but it may come with a longer repayment period and higher total interest costs.
Always compare the total amount you may repay, not just the monthly figure.
Entering an interest rate that is lower than the rate you may qualify for can make a loan appear more affordable than it really is.
Use the rate provided in a genuine financing offer whenever possible. If you do not have an offer yet, treat the result as an estimate.
Some calculators only estimate principal and interest. They may not include application fees, origination charges, insurance, taxes, or other expenses.
Review the lender's terms and add any relevant costs to your budget.
It can be tempting to finance extra equipment or upgrades at the same time. However, borrowing more than necessary can increase both monthly payments and interest costs.
Identify the equipment your business needs and calculate the amount required for that purchase. Borrowing only what is necessary may help control financing expenses.
Equipment financing should support business growth without placing unnecessary pressure on cash flow. Careful planning helps business owners understand their costs before taking on a new financial responsibility.
Smart Business Credit can be part of your process for exploring business financing needs and preparing for equipment purchases. By estimating payments and comparing potential loan terms, you can approach financing decisions with a clearer understanding of your budget.
Before choosing a loan, consider the equipment's expected value to your business. Think about whether it could improve productivity, help you serve more customers, reduce manual work, or support future growth.
Then compare the expected benefits with the full cost of financing. If the equipment can generate enough value to justify the expense, it may be a useful investment. However, the decision should be based on realistic business figures rather than assumptions alone.
An equipment loan calculator can help you reduce financing costs by making loan payments and potential borrowing expenses easier to understand. It allows you to compare interest rates, test different repayment terms, evaluate down payments, and prepare a more realistic business budget.
The most effective approach is to look beyond the monthly payment. Consider the total interest, lender fees, maintenance, insurance, and other expenses associated with owning the equipment. You should also protect your working capital and ensure that the payment remains manageable during slower business periods.